For much of the past decade, investor focus has been placed predominantly on developed markets. However, as growth slows across these economies due to geopolitical challenges and rising fiscal pressure, emerging markets are increasingly attracting investors’ attention.
The IMF expects emerging market and developing economies to grow by around 3.8% this year and 4.5% next year – more than double the pace of advanced economies. While China and India account for a significant share of this expansion, a broader structural shift appears to be under way, with many emerging economies carrying lower debt burdens, stronger external positions and more credible policy frameworks than in previous decades.
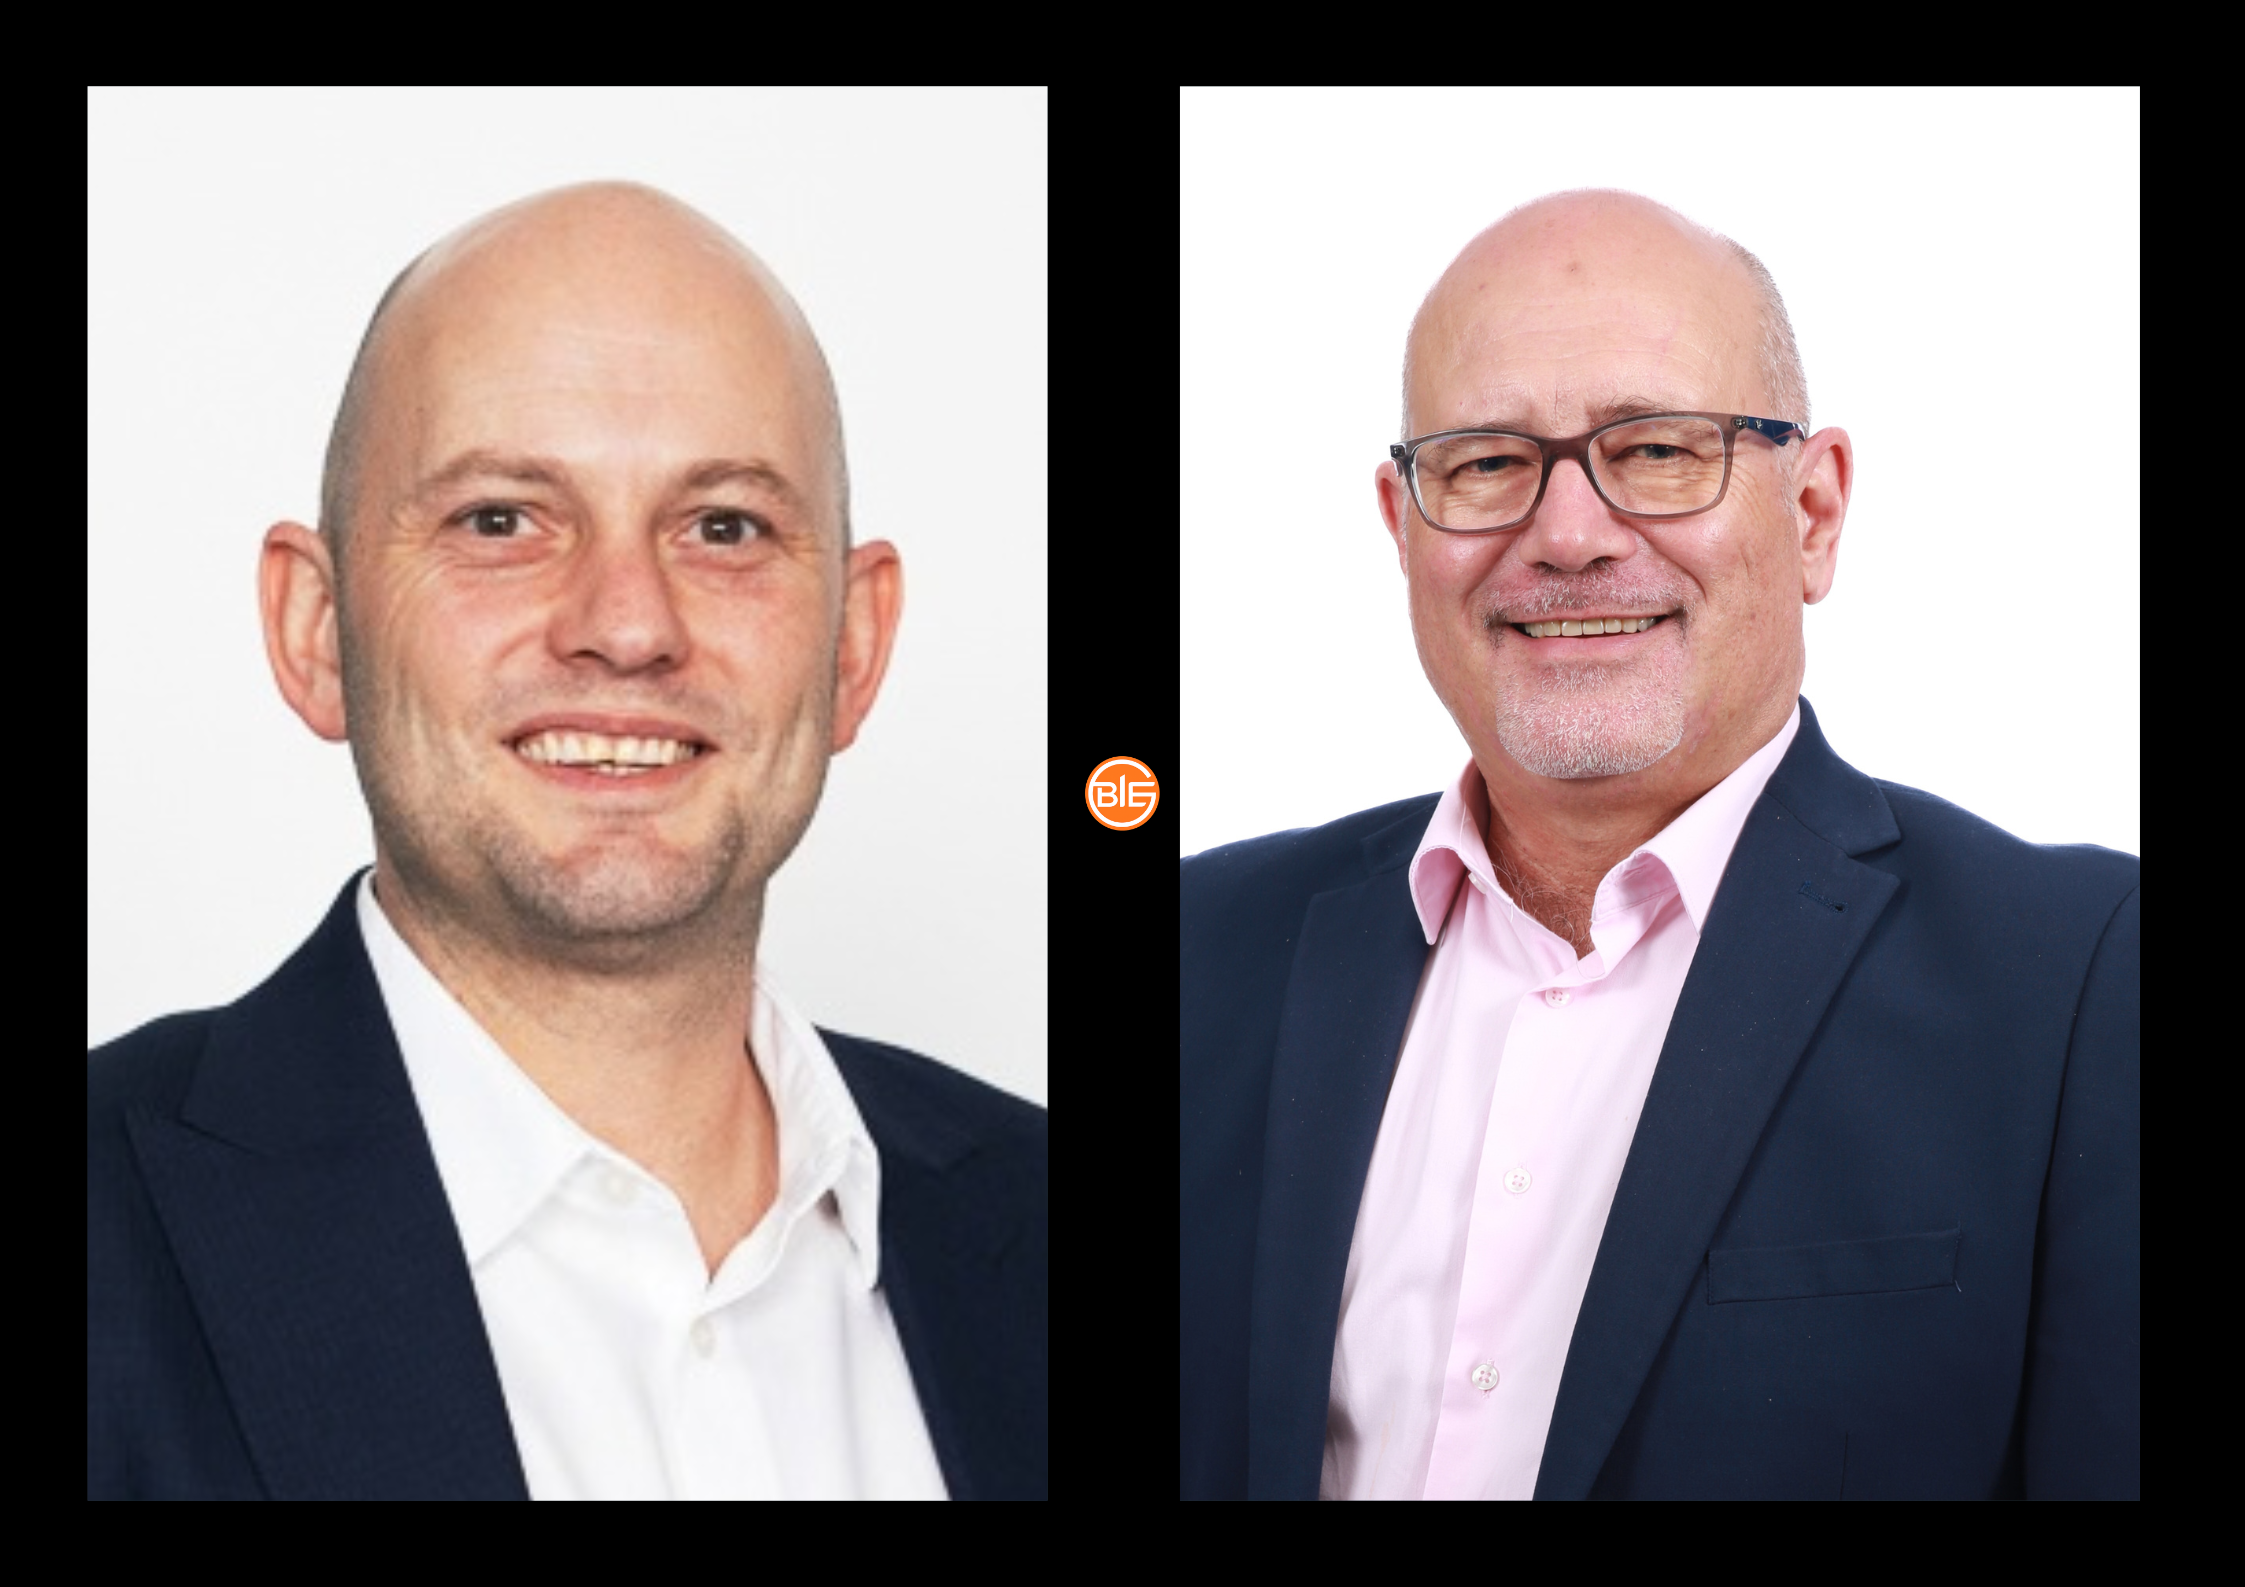
In the latest PSG Think Big webinar, award-winning journalist Alishia Seckam sat down with PSG Financial Services Chief Economist Johann Els and PSG Wealth Chief Investment Officer Adriaan Pask to explore what this could mean for investors.
For Els, the foundations underpinning emerging market growth remain firmly intact. “The growth drivers are still the same as we’ve seen over the past few decades in emerging economies,” he said, pointing to ongoing urbanisation, infrastructure development and rising consumer incomes.
What has changed, however, is the risk profile. “We still call it risk on trade when we invest in emerging economies, but those risks have eased off quite a bit,” said Els, who argues that stronger institutions, improved fiscal and monetary management, and declining debt burdens have fundamentally altered the investment landscape.
The other side of that coin, he adds, is that some of the structural advantages traditionally associated with developed markets have weakened. “Because of slower population growth and other structural issues, we’ve seen that their growth continues to drift lower, but their risks have increased.”
According to Pask, markets have yet to fully reflect this changing reality. “There is a clear gap between market perceptions and the underlying fundamentals we are seeing,” he said. “Obviously, investing in emerging markets is not without risk, especially if you start to venture into equity investments in that space. But that’s where we think the opportunities are rich,” he said.
A major catalyst for a potential re-rating, he believes, is the prediction of a weakening US dollar. “We’ve had a very strong dollar for the past 15 years, and it’s incredibly hard for emerging economies to flourish in that kind of environment.”
A declining dollar, he argues, would ease inflationary pressures, support lower interest rates and improve economic competitiveness across many emerging markets. “That weaker dollar is the real story driving the positive sentiment.”
Importantly, Els stressed that the emerging market growth story extends far beyond China and India, even though they remain major contributors to global expansion. “The rest of global growth is coming from other emerging markets like Indonesia – that’s a fairly big economy as well – and a host of others, such as Brazil, Argentina, Mexico, Turkey, and even South Africa.”
South Africa is an interesting test case as it has historically embodied many of the risks that investors associate with emerging markets – weak growth, fiscal pressure, infrastructure constraints, policy uncertainty, a volatile currency.
Els noted that recent reforms and greater private sector participation are laying the groundwork for a gradual improvement in economic growth. “We’ve essentially solved the electricity problem, thanks to the private sector’s role in electricity generation, and are seeing similar positive developments in other areas like logistics and water too.”
While improvements will take time to filter through the economy, Els believes the foundations for stronger growth are being put in place. “It’s a process, but we’re moving in the right direction. Implementation is still lacking, but we’ve got the policies in place to achieve better growth over the medium term.”
This improving outlook could ultimately support a return to investment-grade status. “I believe we can be back in investment grade within one to three years, but I don’t think that’s priced in yet,” Els notes.
For investors considering emerging markets, both experts emphasised the importance of active management and diversification.
Pask noted that the diversity of economies, sectors and risk factors across emerging markets requires careful portfolio construction and active management. “The benefit is that even though it’s complicated, and all of them have different drivers, that is also what’s your biggest aid because it makes it easier to diversify,” he said. “You can have some commodity exposure in South Africa; some technology exposure through Taiwan and Korea; and consumer exposure through Brazil.”
Ultimately, both Els and Pask believe the combination of stronger fundamentals, improving policy credibility and attractive valuations points to a more compelling long-term outlook for emerging markets than many investors currently appreciate.
“These are structural issues,” notes Els. “It’s not a cyclical uptick in growth for a few years. It’s going to last for a significant time.”
He concluded that while risks can never be eliminated, understanding them remains critical. “You have to be close to those markets that you invest in. You have to understand what’s happening there and you have to look out for signals that might shift the investment landscape.”