Africa faces an estimated $300 billion financing gap for consumers and small businesses — not because the economic activity isn’t there, but because most of it never shows up in a form banks are built to read. A trader with steady daily turnover. A gig worker with reliable, if informal, income. A family that has paid rent in full and on time for years without ever holding a bank loan. To a traditional credit model, all of it is functionally invisible.
South African fintech Notto has built its entire business around closing that gap. The company, which describes itself as Africa’s first licensed alternative credit bureau, isn’t trying to lower the bar for who gets approved for credit. It’s trying to fix the instrument banks use to measure creditworthiness in the first place — and in a few years, it has already put real numbers behind that ambition: more than one billion transaction records analyzed, credit scores built for over eight million consumers, and credit assessments generated for more than five million mobile money users across South Africa, Zambia and Zimbabwe.
A Founder Who Grew Up Inside the Problem
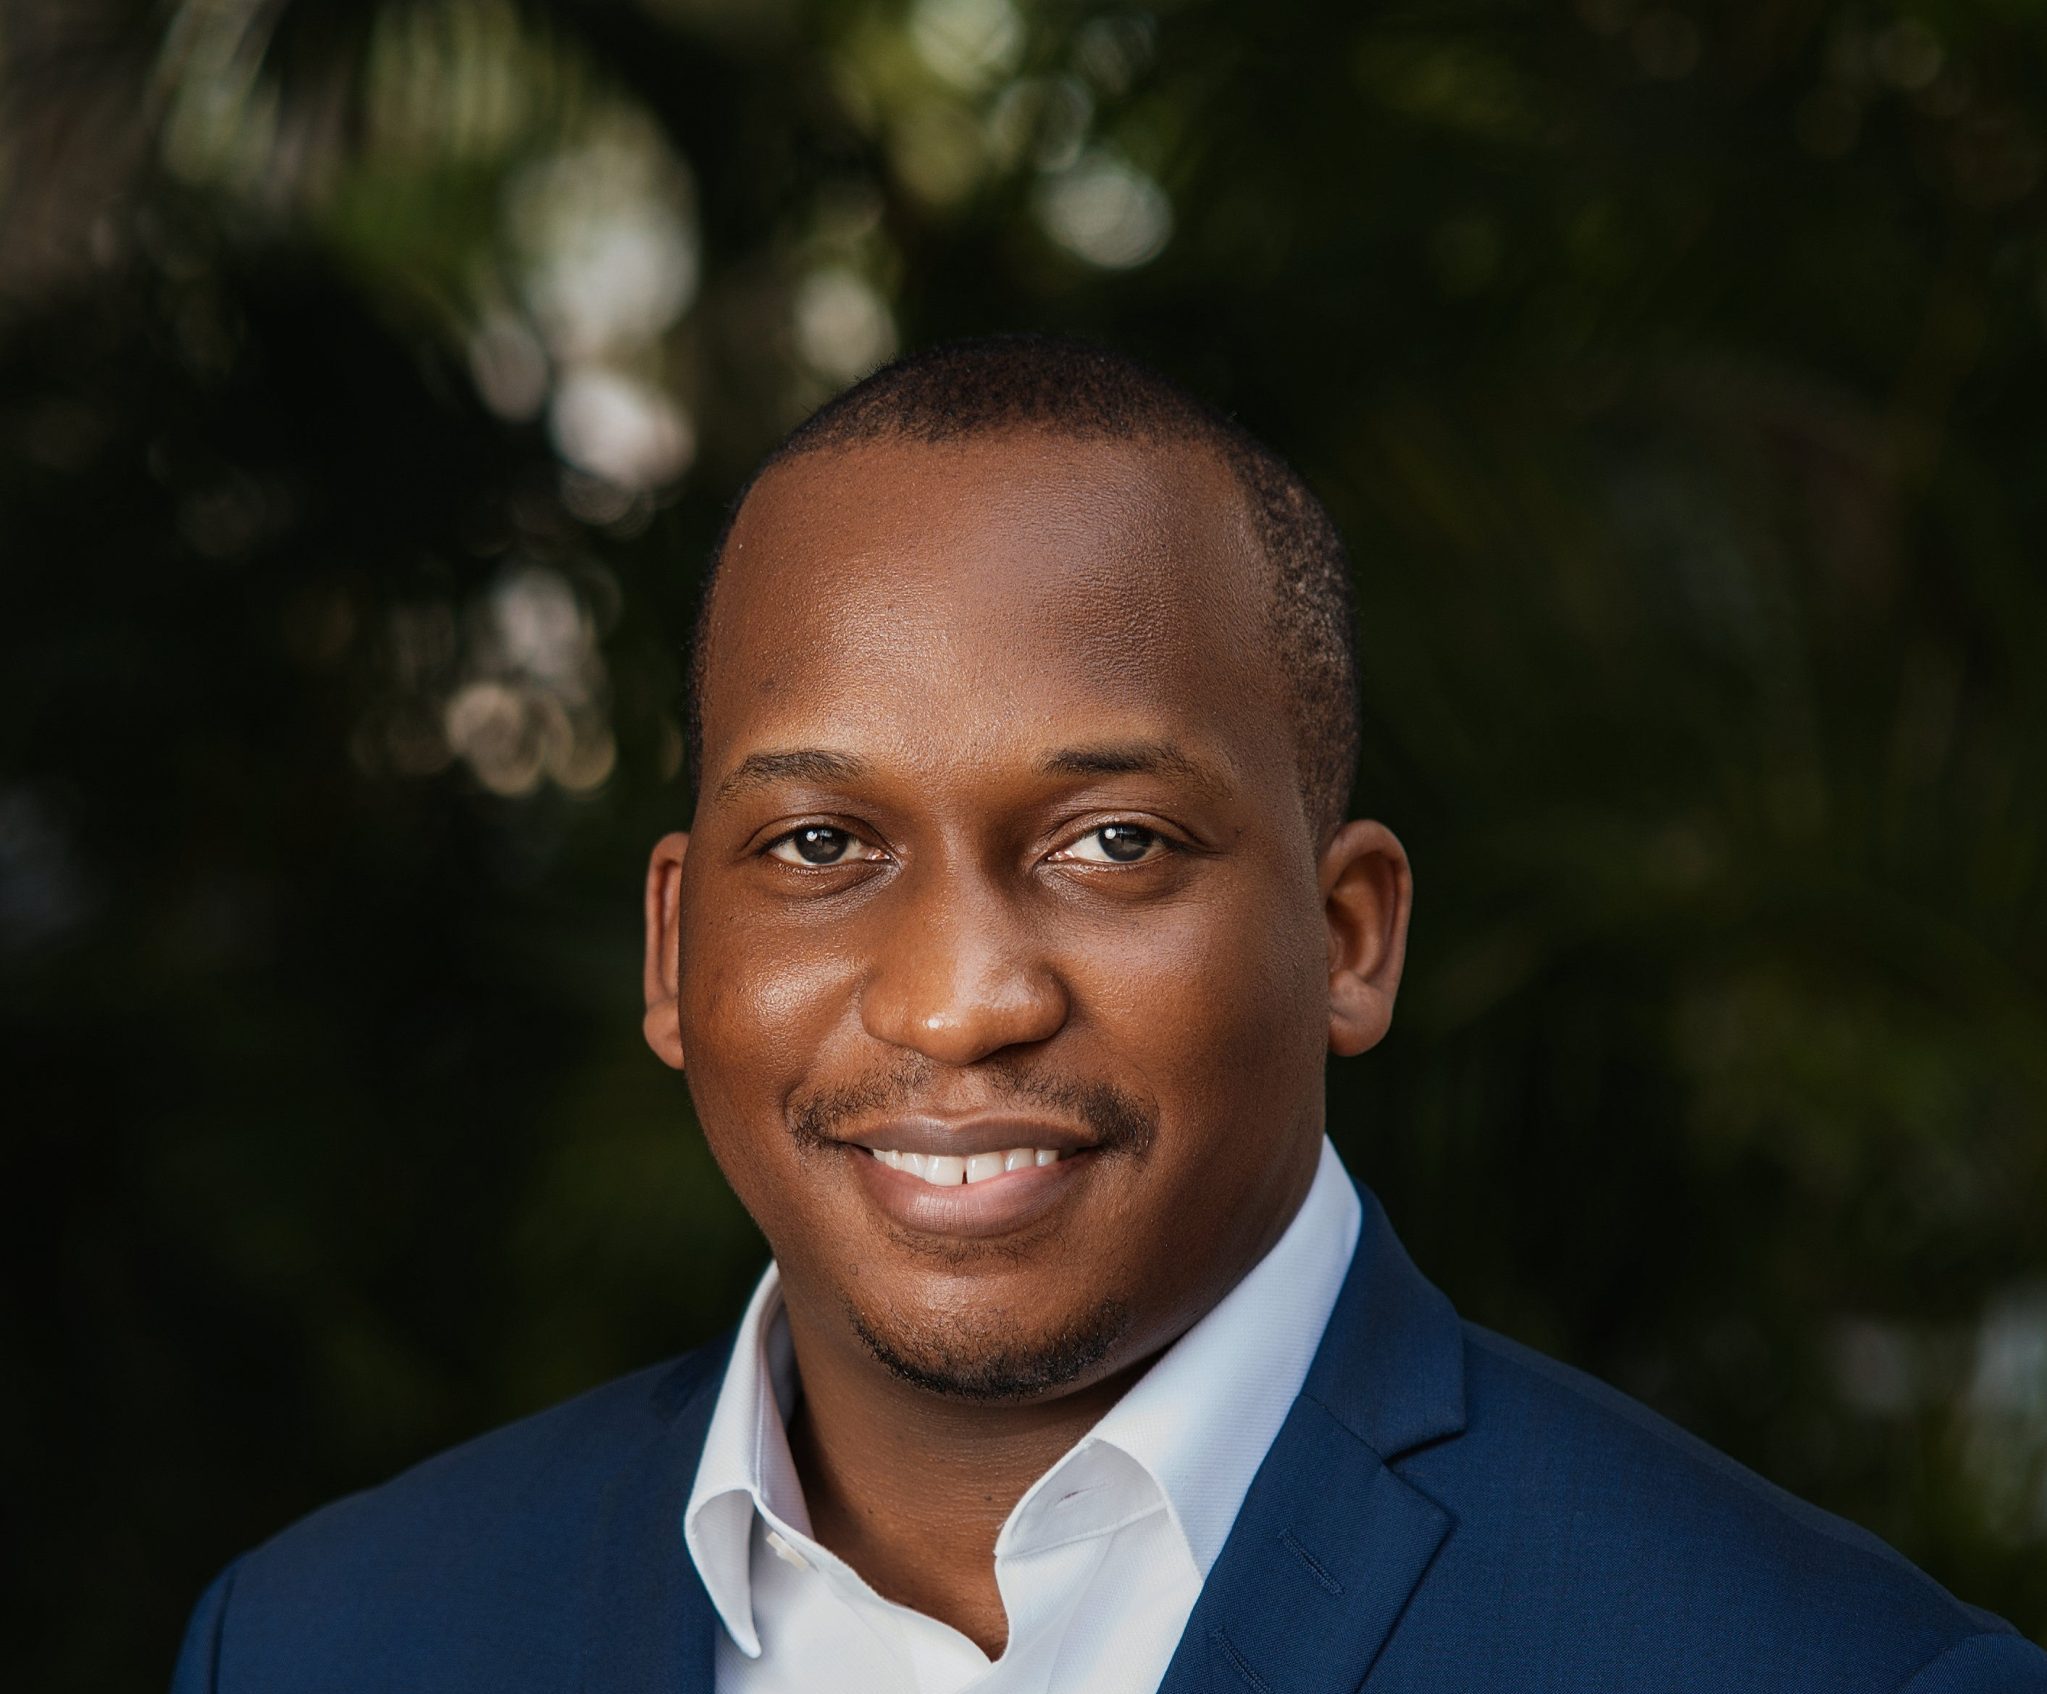
Notto’s founder and CEO, Dalumuzi Mhlanga, didn’t arrive at this idea from a whiteboard. Growing up, he watched a familiar pattern play out around him: families building homes not in a single project but piece by piece over years — a load of bricks one month, a concrete slab the next, then a pause of a year or more before the roof finally went up. To Mhlanga, those unfinished homes were rarely a sign that people lacked money. Many had steady incomes and managed their finances carefully. What they lacked was access to long-term credit.
That observation was sharpened by something closer to home: members of his own family had paid rent in full and on time for years, consistently meeting one of the most significant financial obligations a household can carry, yet still could not qualify for a home loan.
“I grew up in a community where informal trading was a big part of their livelihoods… their growth was contstraint by the cash they had available”
That contradiction became the intellectual and emotional anchor for Notto: a company built on the premise that consistent financial behavior — not just formal paperwork — is real evidence of creditworthiness.
The Problem With How Banks Have Always Assessed Risk
Traditional credit assessment runs on a familiar checklist: formal employment records, payslips, audited financial statements, an existing credit history. For consumers and businesses whose financial lives generate that paperwork, the system works reasonably well. But it leaves out most of the continent.
“From a process perspective, when building alternative credit scores, it is the same as building standard credit scores, with the 5 C’s of credit, Notto uses alternative data to reach a similar result”
Mhlanga has been direct about the scale of what’s being missed: vibrant economic activity exists across the continent, but very little of it currently translates into anything a lender can actually underwrite. Rather than a data problem alone, he frames it as an institutional design problem — banks built their risk frameworks around a kind of borrower who doesn’t represent most of the market.
From a Failed B2C Model to Infrastructure Play
Notto’s current model — partnering with the telcos, payment gateways and fintechs that already hold transaction data — wasn’t the original plan. Mhlanga initially tried to build the business by collecting alternative data directly from consumers, working with tenants and landlords to generate specialized rental-payment credit scores.
It didn’t scale. Data collection that way proved slow, expensive and difficult to grow. The pivot that followed was, by Mhlanga’s own account, a difficult one — but it transformed the company. Instead of gathering raw data itself, Notto shifted to processing data that enterprises already had, building the infrastructure layer that turns existing transaction histories into usable credit intelligence at scale.
“Change isn’t coming at a cost, it is opening up a massive opportunity”
That shift is what allowed Notto to grow from a niche data collector into something closer to plumbing for the region’s credit market.
Artificial Intelligence, Applied to an Old Problem
Notto is careful not to position AI as a credit-scoring shortcut. Instead of relying solely on repayment histories and formal bank records, its models analyze behavioral patterns — regular deposits into mobile money wallets or bank accounts, recurring bill payments, and consistent spending patterns — as signals of a person’s willingness and ability to repay, even when that person has never held a credit card or a formal bank loan.
What AI does, it helps us build these credit scores more effectively and excessively at a scale with much greater sped
The company backs this with an emphasis on explainability and governance rather than black-box scoring: full traceability from signal to decision, audit logs, version control, and continuous monitoring for model drift and bias. For banks and regulators wary of AI systems that hand down scores with no visible reasoning, that auditability is arguably as important to Notto’s pitch as the AI itself.
The Numbers Notto Is Taking to the Banks
For any of this to matter commercially, it has to move the needle for the institutions actually writing checks. And by Notto’s own reporting, it does.
Applying its model to previously underserved populations has increased approval rates by as much as 10x in certain markets, according to Mhlanga, while the share of the population considered creditworthy has climbed from roughly 1% to more than 10%.
Default rates and non-performing loans have reportedly fallen from double digits down to around 3%, alongside an 86% repeat-borrower rate — the kind of retention number that turns a single loan into a long-term customer relationship.
Those figures sit alongside the broader scale Notto has already reached: more than a billion transaction records analyzed and credit scores built for over eight million consumers across the region — numbers that suggest this isn’t an early-stage pilot but a credit infrastructure company already operating at meaningful scale.
“Alternative data can be richer when there is data sharing amongst platforms”
Already Operating Across Three Markets — and Building the Data Layer Between Them
Notto’s next chapter is already underway. Rather than a company preparing to enter the Southern African Development Community, Notto is one already operating inside it: alongside its home base in South Africa, the company has built credit scores and assessments for millions of mobile money users in Zambia and Zimbabwe as well.
“In five (5) years, my ambition and hope are that the data sharing will be rich so thank we really expand”
The longer-term ambition extends past any single market. Banks, telecom operators, mobile-money providers and payment fintechs each hold a different slice of the picture — a telco sees network activity, a payments platform sees transactions, a bank sees formal repayment history — and individually, none of it is complete.
“If we achieve that for alternative data, we will massively open up the credit market across Africa”
That’s the infrastructure layer Notto is trying to own: a secure environment where consented data from multiple industries can be combined into a single, usable financial profile — turning Notto from a single-market credit bureau into connective tissue for African finance more broadly.
Trust Is the Real Product
More data flowing to lenders means more responsibility to the people generating it. As a licensed alternative credit bureau, Notto operates under regulatory obligations that require it to comply with data protection laws and consumer consent requirements in every market it serves.
“We collect consented data, from Teleco, Fintechs and Payment schemes”
That regulatory discipline is arguably Notto’s quiet advantage: in a space where alternative-data lenders elsewhere on the continent have drawn scrutiny over predatory practices and opaque scoring, Notto’s decision to operate as a licensed, audited bureau — with bias and drift monitoring built into the platform — positions it as an infrastructure partner banks can defend to their own regulators, not just a vendor selling a score.
From Credit Score to Financial Infrastructure
The clearest way to understand Notto’s ambition may be this: it isn’t trying to build a better credit score. It’s trying to build the infrastructure that lets financial institutions finally understand customers they’ve spent decades failing to assess.
That reframes the entire question. It’s no longer about whether an informal entrepreneur looks like a traditional borrower on paper. It’s about whether the economic behavior surrounding that entrepreneur — the rent paid on time, the mobile money moved every week, the bills settled like clockwork — provides enough evidence to lend responsibly.
Africa’s informal economy was never inactive. What was missing was the infrastructure to translate that activity into a language traditional finance understands. With more than a billion transaction records processed and eight million credit scores built across three markets, Notto has already gone a long way toward building it.
“Thanks to the South African robust infrastructure, we have learned from the past 5-6 years and Notto is expanding to more African markets”
If the company keeps expanding at this pace, its story will end up being about more than AI or alternative scoring. It will be about redrawing who gets to count as “bankable” across an entire continent.