The rapid and widespread adoption of artificial intelligence (AI) will not replace financial advice, but it will fundamentally change how investors prepare for -important financial planning conversations and the services they are prepared to pay for.
Held over three days in George, Western Cape, the Old Mutual Wealth Investival 26 conference brought together advisers, investment professionals and thought leaders to challenge thinking, exchange perspectives and explore the future of wealth and advice. One of the topics unpacked explored how the emergence of AI financial planning tools could reshape adviser-client relationships. Dan Haylett, CFP® and director for TFP Financial Planning in the United Kingdom, explained that AI was becoming “quite good” at aspects of financial planning, with many investors attending advice meetings with a pre-plan developed by AI tools, and then asking their adviser to ‘sense check’ it.
“Investors of the now and the future are acting very differently to those of three, four or five years ago; we need to understand that they are sense checking our work in ways that can pull it apart,” Haylett said. Francois du Toit, CFP® and founder of PROpulsion, suggested that advisers were increasingly using AI tools to get a second opinion on aspects of their financial advice and completed financial plans.
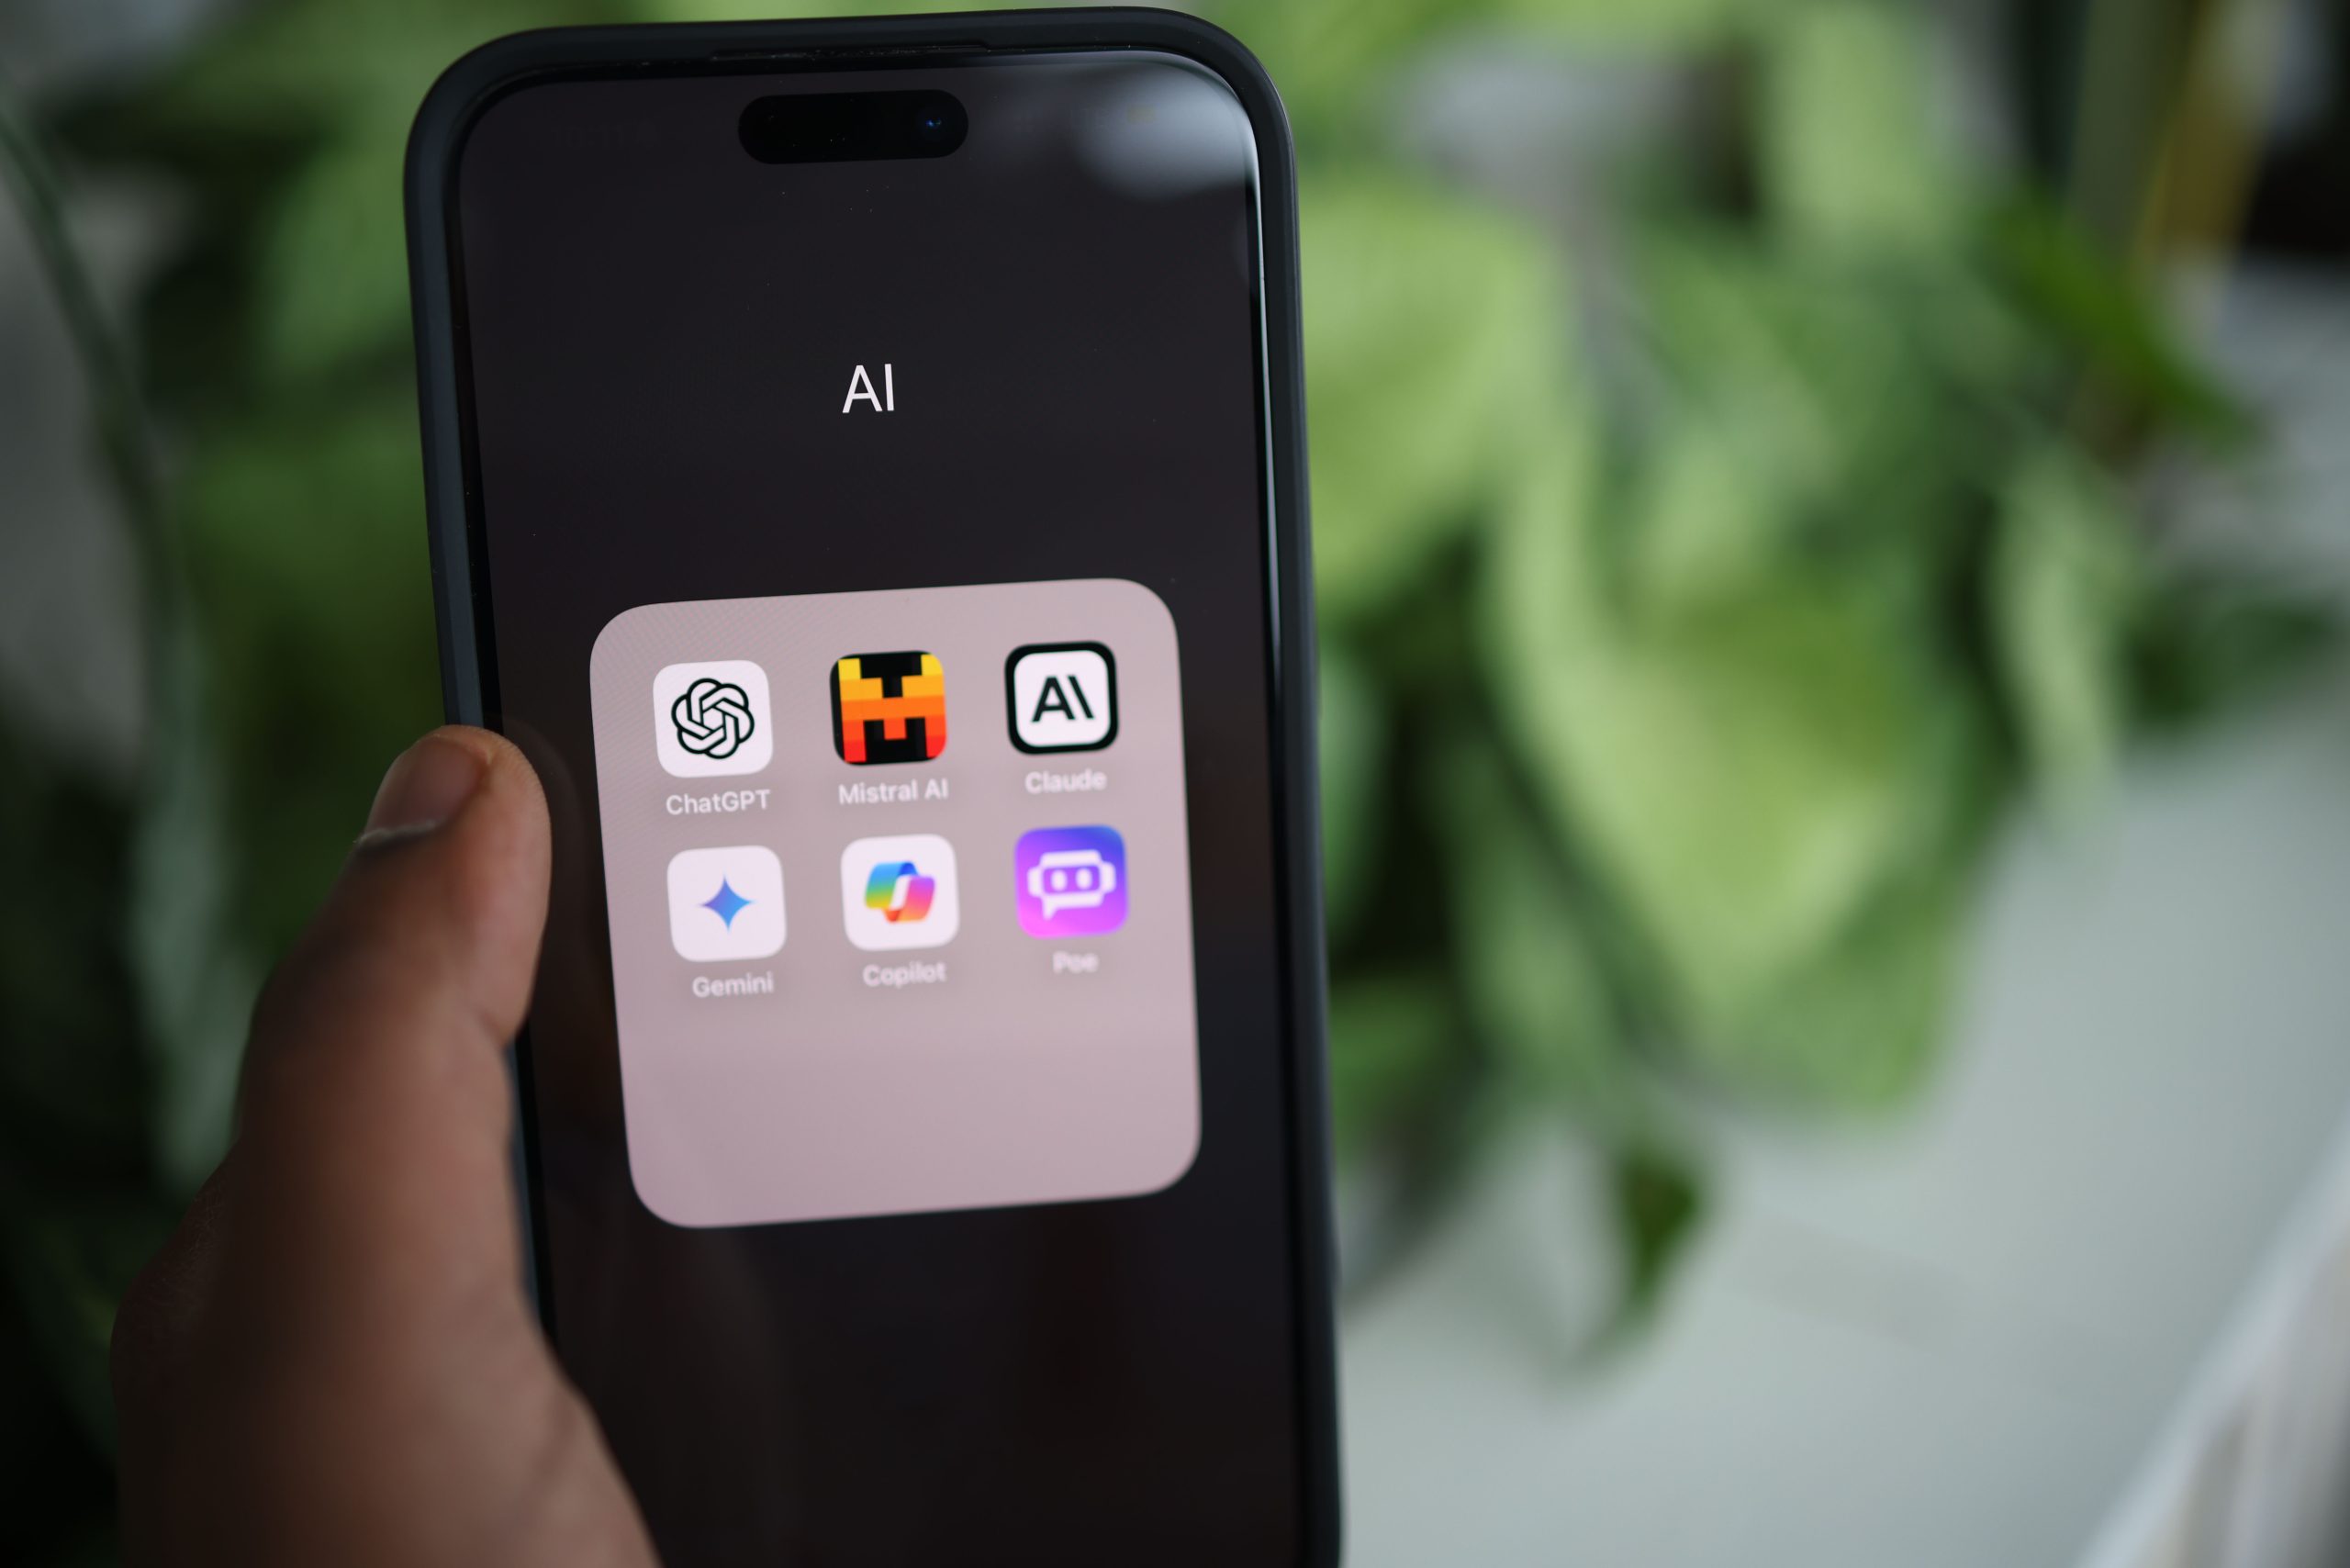
Investors are already using large language models (LLMs) to research financial solutions, and then nodding sagely during advice meetings, saying: “Yeah. Claude told me that too”. They want their advisers to acknowledge the research they have done and use it as a foundation for further discussion, rather than dismiss it. Over time, investors will migrate to planners who hold similar views on how AI and human advice can overlap.
Du Toit noted that LLMs such as ChatGPT and Claude were becoming mainstream tools for young and old. He observed that many prefer the collaborative experience of exploring financial planning solutions with AI to the often nerve-wrecking experience of sitting opposite a human adviser. “Even if we try our very best not to, our clients still fear they are being judged,” he said.
This fear of being judged may explain the rapid uptake of AI among investors interested in offshore markets. A recent STRAT7 research report found that 55% of UK adults used AI for financial advice, and 42% of that group was 55 or older. Furthermore, he UK Financial Conduct Authority has indicated that approximately 11 million UK adults would be willing to use AI to manage aspects of their finances autonomously.
The question that arises is whether AI will lead to a Blockbuster or Kodak moment for the traditional financial advice model. “If our clients are using AI to do a lot of the grunt work for them and coming to us for slightly different services than we currently provide, then we have to take note,” Haylett said. “Otherwise, AI will usher in a Blockbuster moment where we keep doing what we do until our service is not valued or needed anymore.”
As investors realize that technology can assist with their planning needs, they will seek out human advisers who can offer something technology cannot. They will, for example, choose advisers that deliver professional empathy alongside the financial plan and ongoing advice. Du Toit went as far as calling empathy and human connection safeguards for the advice profession.
The caveat here is that advisers have limited capacity to establish deep and lasting friendships with every client. Investors are, therefore, better served by a professional rather than a friendship-based relationship with their adviser. That said, there is a definite planning advantage for investors when their financial advisers have a deeper understanding of their clients and their goals.
The technical information ‘edge’ sits firmly with AI and LLM, giving everyday investors access to information across all areas of financial planning. “Clients are more educated and knowledgeable than they have ever been,” Haylett said. And this means that technical knowledge is far less important than knowing what matters to the investor seeking financial advice.
Ironically, the same AI technology investors are embracing can help advisers understand their clients better. For example, AI can analyse recorded client conversations to assess behavioral patterns, identifying triggers are and allowing advisers to respond effectively in real-time.
Whether tomorrow’s investor favours a human adviser or not, the idea of engaging with an AI adviser is already becoming a reality. Investors can now have interactive discussions with personal assistant AI agents and get immediate responses to financial planning questions. Looking for an upside, Du Toit suggested that AI would lead to more rather than less adviser-client engagement.
“AI is going to build that bridge to a large extent, and we should give clients permission to interrogate it. They will feel more comfortable coming back and having a conversation with us rather than going somewhere else, or even worse, not coming back at all,” he said.
When investors question AI about advice, asset management and platform fees, responses may reflect the negative sentiment fees in the information on which these models are trained. Advisers can respond by embracing AI themselves and encouraging their clients to also use it constructively. They can also switch places with the client, using AI to interrogate their own advice and financial planning from the client’s perspective.
Major advice shifts are underway in financial advice, underpinned by technology. In the US, Vanguard has taken steps that caused major ripples in the US wealth management market by agreeing to acquire Altruist, an AI-forward wealth technology and custody platform for financial advisers. Its Hazel platform now includes tax and financial planning capabilities which means that investors may soon meet all of their advice needs on tech-enabled platforms, be they digital- or AI-driven.
The evolution of financial planning should not be seen as a battle between human advisers and AI. “This is not AI versus the adviser,” concluded Haylett. “This is AI combined with human expertise when investors need it, versus an advice model where the adviser meet the client once a year for little more than a coffee and a chat.” The future of financial advice is not about choosing between AI or the human expert. It lies in bringing the two together, and increasingly, that is what investors will expect.