Residential house prices have risen quickest in percentage terms in the lower price bands over the last ten years, but the gap between the higher and lower bands has widened. At the same time, homeownership among younger buyers has declined.
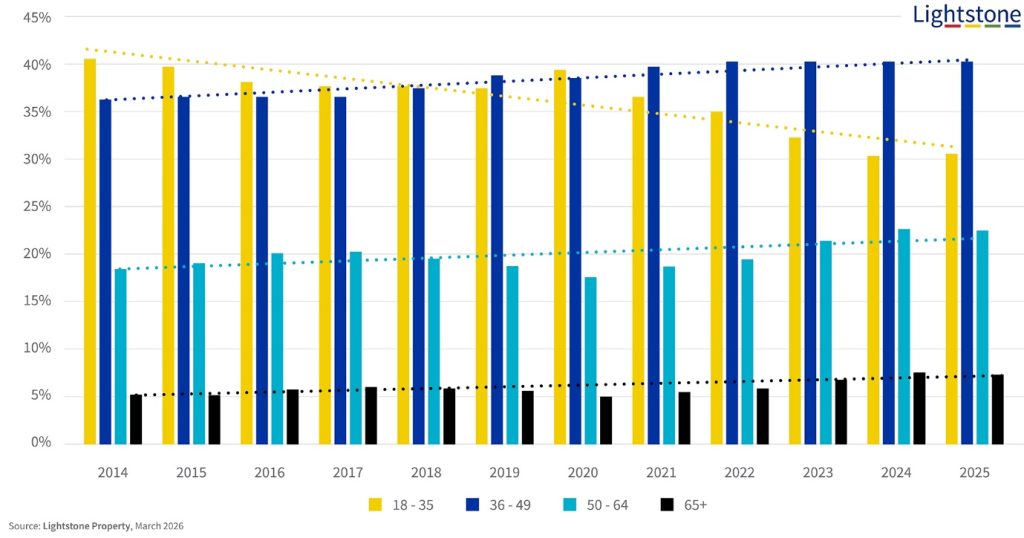
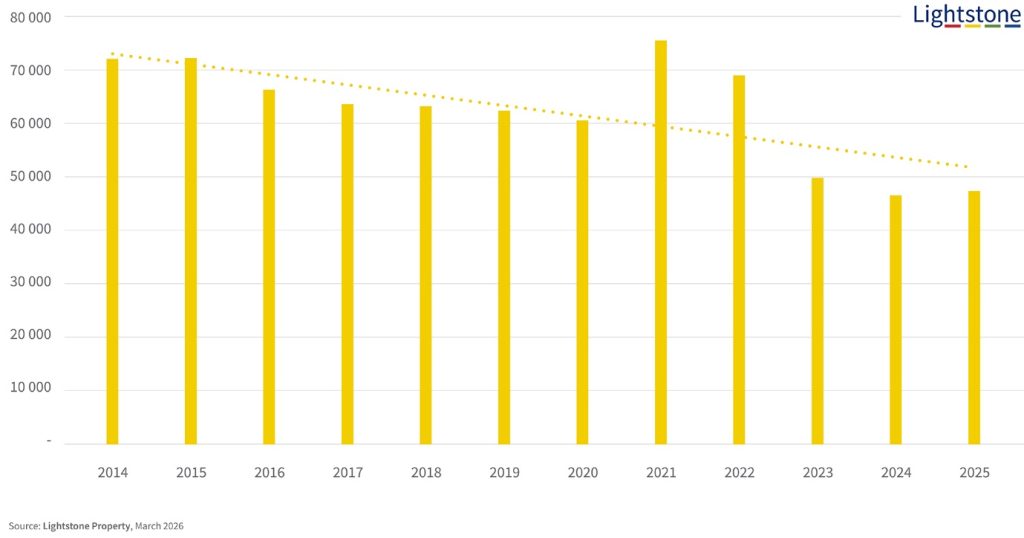
“Our analysis of data from 2014 – 2025 confirms that property volumes have drifted downwards while prices have escalated most significantly in the higher price bands. Perhaps most revealing – and worrying – is the decline of buyers between the ages of 18-35, both in percentage terms from 40% to 30% but also in absolute numbers from 72 000 in 2014 to 47 000 in 2025”, says Hayley Ivins-Downes, Managing Executive Real Estate at Lightstone Property.
In fact, economists, policymakers, and institutions like the Organisation for Economic Cooperation and Development (OECD) and International Monetary Fund (IMF) have increasingly described this as a structural affordability problem, not just a temporary cycle.
Age distribution of natural buyers: 2014 – 2025
Number of properties bought by 18-35 year olds: 2014 – 2025
“There are several reasons behind the drop in younger buyers. They include lifestyle changes, house prices rising faster than wages, large deposit requirements, higher student debt, stricter mortgage rules following the 2008 global financial crisis, and in some cases, a lack of confidence in government or in the future. Implicit in this shift is a wealth transfer from young to old. We are seeing that the younger people rent from older people, often paying higher proportions of their income for housing. In the process, housing wealth has shifted towards older generations,” adds Ivins-Downes.
If this continues, several structural outcomes are likely, and they include:
- A permanent renter class emerges as homeownership is delayed or unattainable for many younger households. Large institutional landlords may expand or emerge where they don’t exist.
- Slower household formation as young people move out later and delay having children. This already appears to be happening in several countries.
- Political pressure and policy intervention as housing affordability grows in importance as a major political issue. Possible responses could include rent controls, large-scale housing construction, taxes on investors, and inheritance taxes on housing wealth.
- Long-term demand risk for housing markets. Ironically, if young buyers never enter the market, future housing demand could weaken. Housing markets historically rely on first-time buyers moving up the ladder. If the ladder breaks, transaction volumes will fall and prices become dependent on wealth transfers (inheritance, family help).
Volumes drifting
So, where is South Africa trending? Residential property volumes have declined from 247 000 units sold in 2014 to 218 000 units in 2025, with just the Covid-bounce years of 2021 and 2022 bucking the trend.
Property volumes: transactions 2014-2025
Rising prices at the top end
Younger buyers have dropped and volumes have too, but what has happened with property prices and the mix of properties?
At the higher end (High Value and Luxury segments) considerations include asset inflation and capital flows (housing has become an investment asset and a store of wealth, not just shelter); supply constraints (due to zoning, planning restrictions and local opposition to development); demographic factors (older homeowners stay longer in homes, downsize less often and hold large amounts of housing wealth, all of which reduces turnover); and monetary policy (long periods of low interest rates after the 2008 crisis pushed asset prices higher, including housing).
Escalation of property prices in different area types
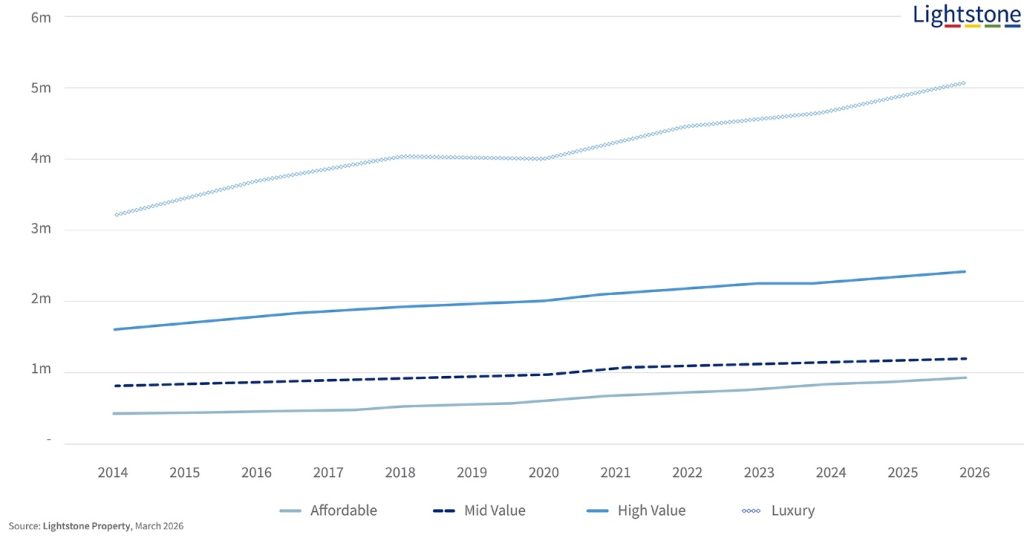
The graph above demonstrates the growing gap between Luxury and other price bands, although the growth in percentage terms at 156% was less than Affordable (230%) but slightly more than High Value (150%) and Mid Value (141%).
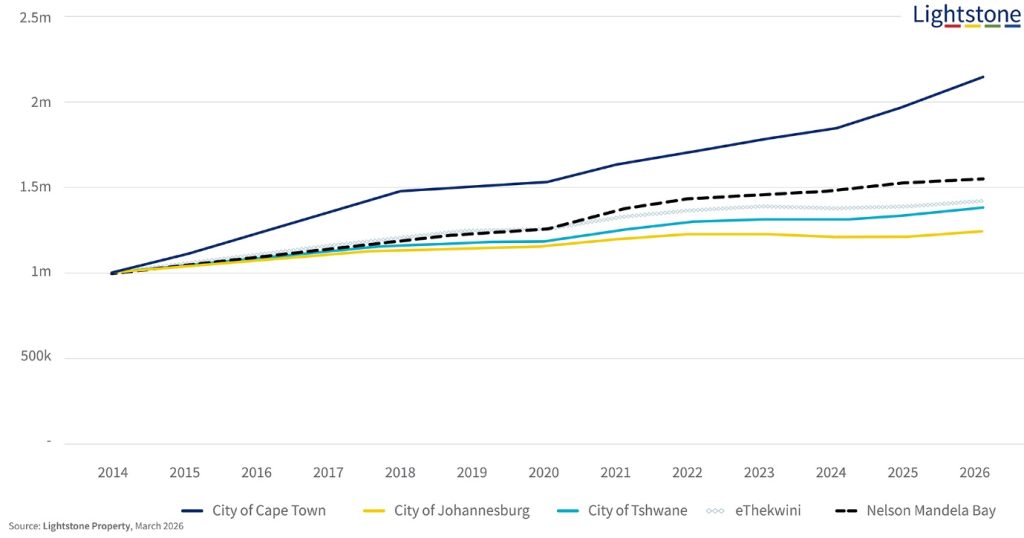
The price of a home is not universal, though, and the graph below shows the difference a municipality can make – a property that cost R1m in 2014 would now cost R2.1m in Cape Town, R1.5 in Nelson Mandela Bay, R1.4m in eThekwini and Tshwane and just over R1.2m in Johannesburg.
What a R1m property in 2014 would cost in 2025
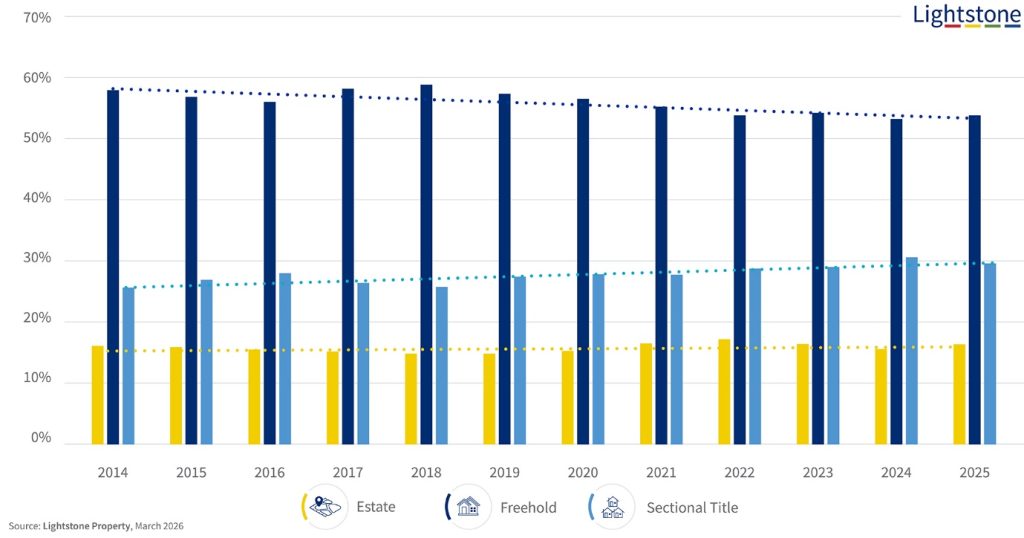
If we look at the sales volumes and property type (graph below), we see the gradual decline of Freehold sales over the years mirrored by the slow growth of Sectional Title properties. Estates as a percentage has more or less remained static.
Sales volumes per property type: 2014 – 2025
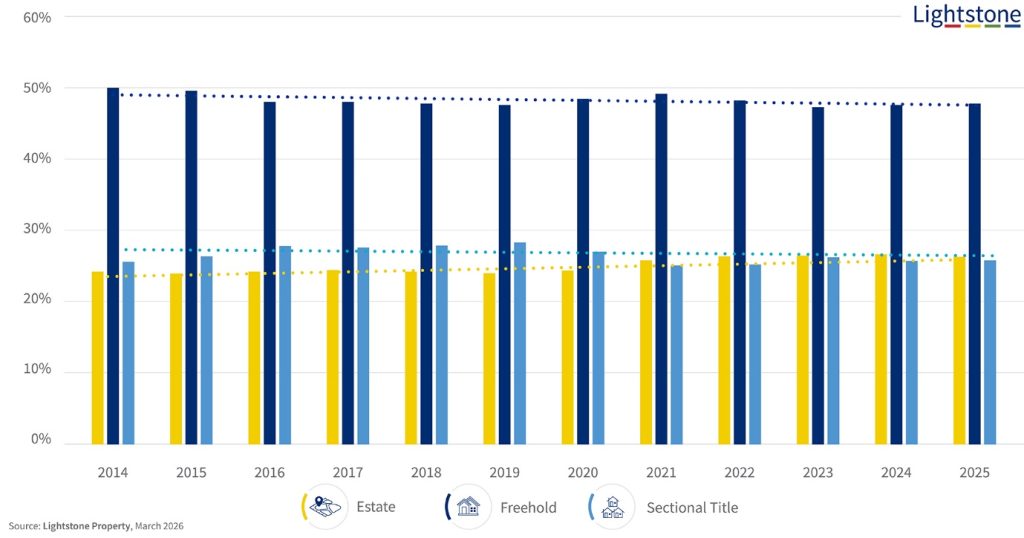
When it comes to value of sales, Freehold has slipped from 50% in 2014 to 48% in 2025, while Sectional Title has nudged upwards from 25.6% to 25.8% and Estates have moved from 24% to just over 26%. The trend is holding and lifestyle changes, which came during and immediately after Covid, could partly explain the shift.
Total sales value per property type: 2014 – 2025
Where to from here?
“South Africa’s housing market is resilient all round and robust in parts. Stabilising forces include population growth and immigration, which raise demand, and limited housing supply prevents large price drops. Business and investor confidence in the Western Cape drives the property market forward, and there are pockets elsewhere in the country where the higher price bands do well, such as the KwaZulu-Natal North Coast, parts of the Eastern Cape and the area around Hoedspruit,” says Ivins-Downes.
The likely outcome in many residential property markets without reform is lower homeownership, higher rents and greater wealth inequality.