While excess is a standard feature of most short-term insurance policies, it remains a concept that is widely misunderstood, with many policyholders only really discovering how it works when something goes wrong or during claim stage.
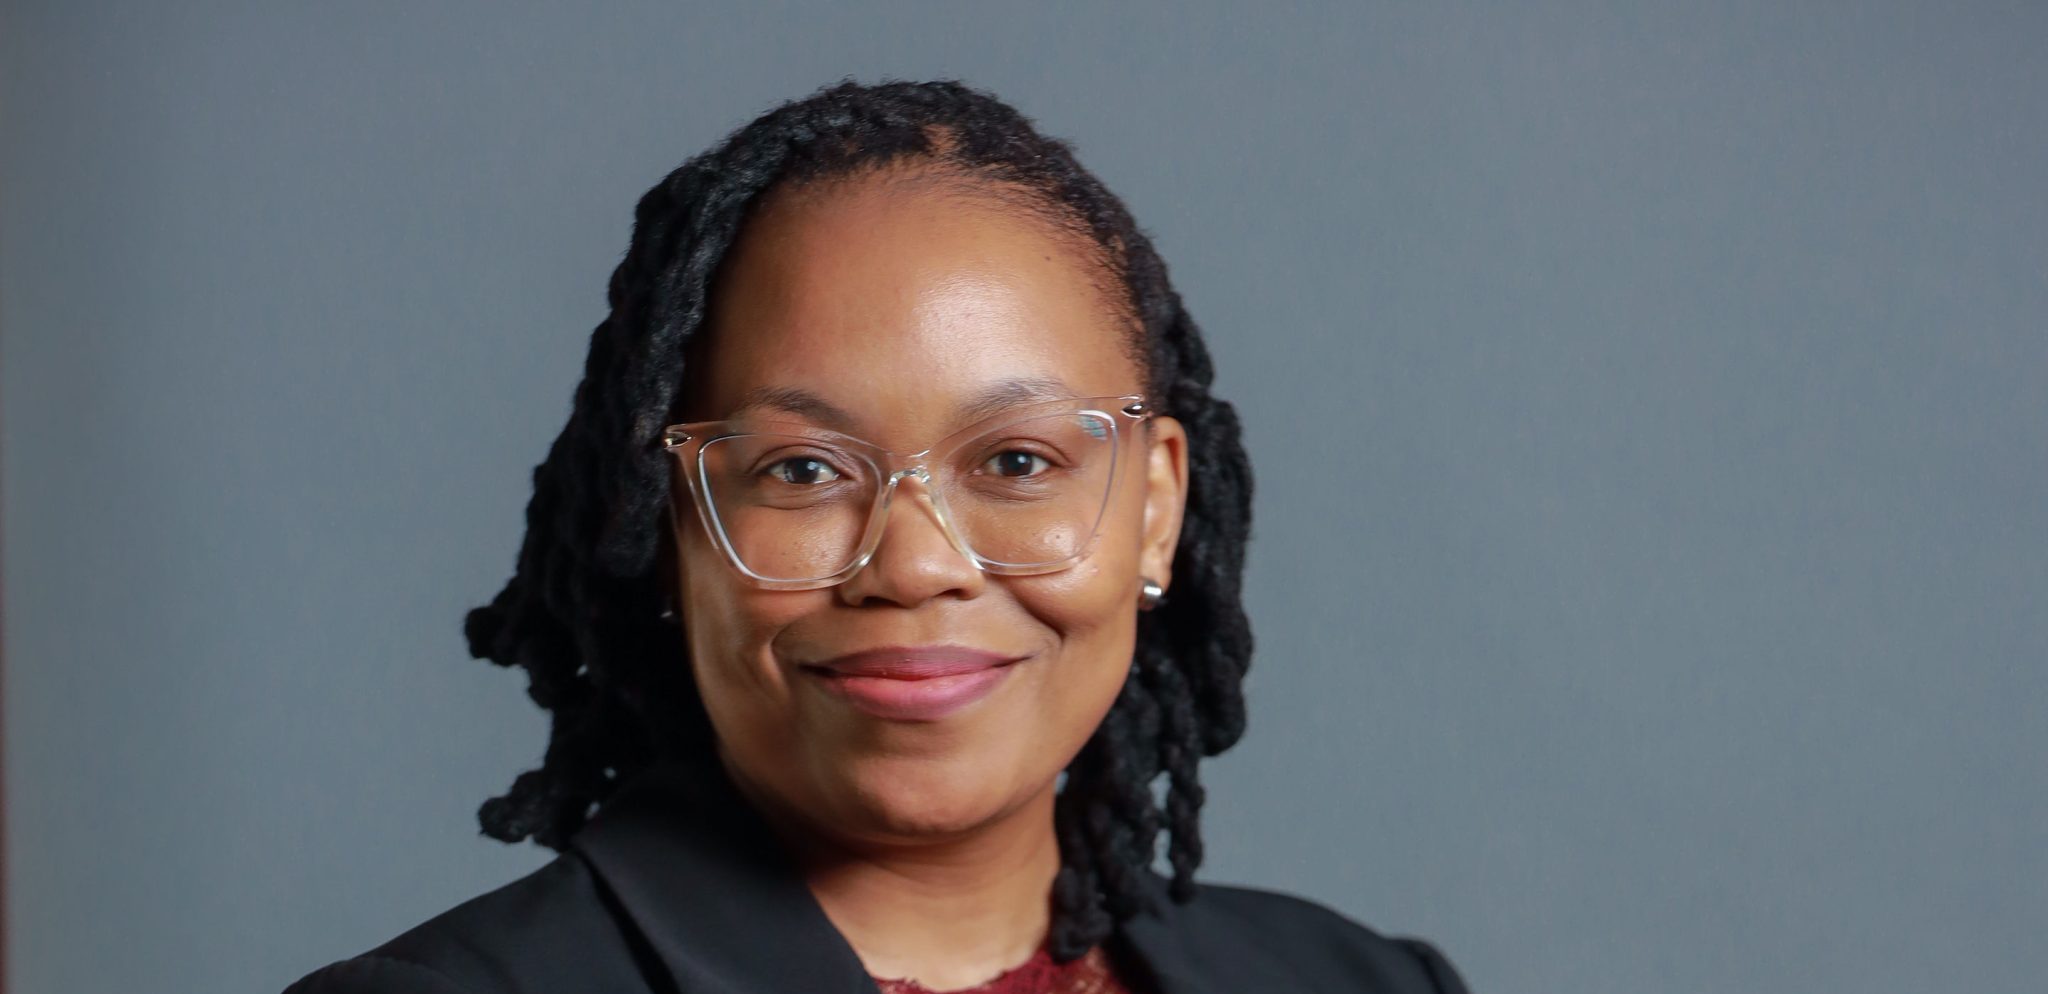
According to Sherry Sibeko, Executive Head of Personal Lines at Miway Insurance, who says that understanding your insurance excess is essential because it plays a direct role in determining both premiums and the first amount payable at claims stage.
“In simple terms, an excess is simply the portion of a loss or claim that the policyholder agrees to pay out of pocket before the insurer will pay the balance,” explains Sibeko. “But what many people misunderstand is that the amount and structure of excess payable can vary significantly between policies, as well as from one person to another.”
The premium-excess trade-off
The first thing to understand, she says, is that there’s generally an inverse relationship between excesses and premiums. “This means that the higher your excess is set at, the lower the monthly premium you will pay, and vice versa.”
A helpful way to think about it is that opting for a higher excess means assuming more financial responsibility at claim stage. “Therefore, it is important for policyholders to understand the implications when choosing or agreeing to an excess, “The right choice depends entirely on your personal circumstances, your current financial situation and your ability to absorb unexpected costs should you need to claim,” says Sibeko.
For example, some people may choose a higher excess because it helps make their insurance more affordable from month to month. “This should be a careful consideration provided that you have savings or safety net for covering that excess in the event that you need to claim,” she says.
How your excess is calculated
A common misconception is that excess is determined solely by what a person can afford.
“While affordability plays a key role towards the amount, you’re comfortable with, insurers consider a broad range of factors when assessing your risk profile and determining premiums says Sibeko. Premiums are determined based on individual risk profiles.
As a result, two people with similar policies may have different premiums and excess structures/amounts.
“Newly licensed drivers may pay higher insurance premiums than more experienced drivers with a proven, claim-free track record, as they have had less time to demonstrate their driving behaviour. As a result, some younger or less experienced drivers may opt for a higher excess, which can help reduce their monthly insurance premium.”
Make the decision that’s right for you
Because there are so many factors involved, choosing the right excess should never be treated as a simple tick-box exercise. Instead, Sibeko urges policyholders to take the time to understand how excess works, ask questions and discuss their circumstances openly with their insurer.
“Insurance is not one-size-fits-all, and neither is excess,” she says, adding that when properly understood, it can be a valuable tool that helps to build cover that is both practical and sustainable over the long term.
“By working closely with your insurer, you can be sure you’re making an informed decision and have peace of mind knowing that your excess aligns with your lifestyle, budget and overall risk profile,” Sibeko concludes.